
The Best Multi-Currency Accounts in South Africa in 2026
Table of Contents
Author: Artiom Pucinskij
Table of Contents
Shyft is my top pick for app-based ZAR funding and travel, while FNB Global Account suits existing FNB customers wanting separate foreign-currency accounts.
Wise is my choice for receiving foreign income, although you cannot fund it directly from ZAR or order a new Wise card in South Africa.
Standard Bank Optimum is the offshore alternative, while Nedbank, Absa and Investec cover more specific local holding, saving and spending needs
Holding foreign income
Wise lets you receive supported foreign payments and hold over 40 currencies without a monthly fee.
You can keep foreign earnings for future overseas payments, although direct ZAR funding and new Wise cards are unavailable.
Foreign balances with card access

FNB lets existing customers open accounts in nine foreign currencies, with dedicated cards available for USD, GBP and EUR.
There is no monthly account fee or minimum balance, making it practical for keeping foreign earnings and spending them later.
Multi-currency accounts work differently in South Africa
A multi-currency account can mean an app wallet, separate foreign-currency accounts at a local bank, or an account legally held offshore.
That difference affects how you add ZAR, receive foreign money, use a card and protect the balance if the institution fails.
Local bank accounts usually work better when your money starts in rand, while Wise is more useful when the money already arrives in a supported foreign currency.
At a glance
In my opinion these are the best multi-currency account options right now:
App-based ZAR funding and travel: Shyft
Foreign-currency accounts for existing FNB customers: FNB Global Account
Receiving and holding foreign income: Wise
Building local foreign-currency savings: Nedbank Foreign Currency Account
Holding a broad range of currencies locally: Absa Currency Investment Account
Card spending for Investec private clients: Investec Multicurrency Pockets
A bank account held offshore: Standard Bank Offshore Optimum
Before opening an account, make sure to check the funding route, receiving details, card settlement, total costs and legal entity holding your money.
Best multi-currency accounts in South Africa
"Over 15 million customers use Wise, mostly for their excellent mobile app, transparent fee structure & use of mid-market rates. Now increasingly used for larger transfers."
Shyft
Shyft lets you buy four currencies from ZAR and spend from matching travel wallets.
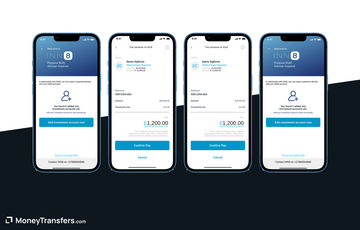
Key information | Shyft |
|---|---|
Type | Standard Bank app wallet |
Eligibility | Age 18+, SA resident; foreign nationals need an active Standard Bank account |
Currencies | ZAR, USD, GBP, EUR and AUD |
Funding and receiving | ZAR by EFT or card, matching-currency international receipts |
Card | Physical multi-currency card and virtual cards |
Main costs | 2.5% card top-up, 0.5% foreign-currency card spend, R100 physical card |
Protection | Standard Bank wallet; confirm the wallet-specific protection terms |
EFT funding avoids the 2.5% card top-up charge, saving R250 when you add R10,000 before the currency conversion.
Shyft sets the exchange rate when you buy foreign currency, so the absence of a separate conversion commission does not mean a spread-free exchange.
Ordinary incoming and outgoing international payments cost US$14, £10, €12 or AU$18 before possible correspondent-bank deductions.
A US$14 receiving fee consumes 7% of a US$200 payment, compared with 0.7% when the payment is US$2,000.
This makes Shyft better for ZAR-funded travel and larger receipts than frequent small foreign payments, especially when Wise can receive domestic USD payments such as ACH for free.
Give the sender the matching wallet’s beneficiary details and reference so the incoming payment reaches the correct currency balance.
FNB Global Account
FNB Global Account offers existing customers several currency accounts and dedicated USD, GBP or EUR cards.
Key information | FNB Global Account |
|---|---|
Type | Separate local foreign-currency accounts |
Eligibility | SA resident taxpayer, age 18+, qualifying FNB cheque account |
Currencies | USD, GBP, AUD, EUR, INR, CNH, CAD, CHF and AED |
Funding and receiving | Linked FNB account, with eligible foreign earnings received directly |
Card | Debit and virtual cards for USD, GBP and EUR |
Main costs | No monthly account fee, card and payment charges apply |
Protection | Qualifying South African-booked deposits may receive CODI cover |
There is no minimum balance, and transfers between the linked FNB account and Global Account carry no separate transfer fee.
You still pay through FNB's exchange rate when moving between ZAR and foreign currency, with international payment costs assessed separately.
The virtual card is free, while annual physical-card fees are £22, US$28 or €26 for the matching account currency.
I would use the virtual card for online payments unless cash withdrawals or physical card acceptance justify that recurring fee.
Foreign ATM withdrawals cost £3, US$5 or €4 before any operator charge, while spending in a different currency zone adds a 1.5% cross-currency fee.
That fee equals US$15 on a US$1,000-equivalent purchase, so match the card currency to the transaction whenever possible.
Wise
Wise gives you foreign receiving details and lets you hold more than 40 currencies.
Key information | Wise Account |
|---|---|
Type | International payment account |
Eligibility | Verified South African resident, age 18+ |
Currencies | More than 40 supported currencies |
Funding and receiving | Foreign receipts through eligible account details, no direct ZAR-funded transfer |
Card | No new Wise card for South African residents |
Main costs | No monthly fee, separate conversion and payment charges |
Protection | Safeguarded electronic money, without bank deposit insurance |
South African residents can hold money with Wise, and account details are free when available for the required currency.
Domestic non-wire receipts in supported currencies, including USD ACH, GBP and EUR payments, can arrive free of a receiving charge.
Incoming USD wires cost US$6.11, while SWIFT receipts cost £2.16 in GBP or €2.39 in EUR before possible correspondent deductions.
I would ask a US payer to use ACH where possible, because a domestic wire would still trigger Wise’s receiving fee.
The limitation is funding, because Wise does not currently support sending from ZAR into the account or through its transfer service.
Keeping received dollars for a future dollar payment avoids converting them into rand and buying dollars again later.
Nedbank Foreign Currency Account
Nedbank’s Foreign Currency Account suits existing customers building an interest-bearing currency balance.
Key information | Nedbank Foreign Currency Account |
|---|---|
Type | Local foreign-currency savings and investment account |
Eligibility | Age 18+, eligible residence documents and Nedbank current or savings account |
Currencies | USD, GBP, EUR, AUD, CAD, HKD, ILS and JPY |
Funding and receiving | Linked Nedbank account with exchange-control documentation where required |
Card | Separate Travel Card funded from the FCA |
Main costs | No monthly fee, separate conversion, payment and Travel Card charges |
Protection | Qualifying South African-booked deposits may receive CODI cover |
Digital opening needs one unit of the selected currency, while assisted opening requires the equivalent of R1,500, making the app route more accessible.
Digital transfers between a Nedbank transactional account and the FCA, or between FCAs, carry no separate transfer fee.
The exchange rate still determines the ZAR conversion cost, and an international payment can add SWIFT and correspondent-bank charges.
Loading the separate Travel Card costs 2.2%, with a R140 minimum, so loading R5,000 costs R140 rather than the R110 percentage calculation.
I would keep this account for saving or future foreign payments, then use a dedicated travel wallet when frequent card spending is the priority.
Absa Currency Investment Account
Absa’s Currency Investment Account offers existing customers a choice of 18 foreign currencies.
Key information | Absa Currency Investment Account |
|---|---|
Type | Local foreign-currency investment account |
Eligibility | Age 18+, SA ID, tax number and Absa current account |
Currencies | 18 foreign currencies |
Funding and receiving | Linked Absa transactional account through international inter-account transfer |
Card | Separate Multi-currency Cash Passport for travel spending |
Main costs | No monthly fee or minimum balance, exchange and payment costs apply |
Protection | Qualifying South African-booked deposits may receive CODI cover |
I would use it to hold the currency of a future overseas bill, rather than converting that money back into rand between payments.
Conversion and international payment charges still apply, despite the absence of a monthly account fee.
Check the full conversion and payment cost before funding the account.
Transferring money to the separate Cash Passport introduces its own card terms and fees.
I would choose Absa when its 18-currency range covers a less common balance that Shyft, FNB or Investec does not support.
Investec Multicurrency Pockets
Investec Multicurrency Pockets let private clients spend USD, GBP and EUR with one card.
Key information | Investec Multicurrency Pockets |
|---|---|
Type | Foreign-currency pockets inside a South African Private Bank Account |
Eligibility | Existing Investec Private Bank client; general income entry R800,000 a year, with other qualifying routes |
Currencies | USD, GBP and EUR |
Funding and receiving | ZAR conversion, pocket transfers and eligible international receipts |
Card | Existing physical or virtual Investec Visa |
Main costs | Pockets free, underlying Private Bank Account costs R705 monthly |
Protection | Qualifying South African-booked deposits may receive CODI cover |
With Intelligent Routing enabled, your card selects the funded matching pocket, avoiding a card conversion charge when that balance covers the purchase.
If the pocket cannot cover the whole purchase, the transaction falls back to rand and incurs the applicable foreign-currency card fee.
The pockets themselves are free, but the required Private Bank Account costs R705 monthly, equivalent to R8,460 each year.
Qualifying under-30 professionals pay R355 monthly, still producing a R4,260 annual account cost before exchange or international-payment charges.
That makes Pockets useful for someone who already wants Investec private banking, rather than a reason to open the underlying account for occasional travel.
Investec's separate Foreign Currency Call Account suits private clients wanting interest-bearing USD, GBP or EUR holding without the same card-spending focus.
Standard Bank Offshore Optimum
Standard Bank Optimum offers offshore banking for South African residents.
Key information | Standard Bank Offshore Optimum |
|---|---|
Type | Offshore current account in one selected currency |
Eligibility | Age 18+, accepted SA-resident application, identity/address checks and opening deposit |
Currencies | GBP, USD, EUR or AUD |
Funding and receiving | International payments, standing orders and GBP direct debits |
Card | Optional Visa debit card |
Main costs | Opening and quarterly balance thresholds, card and payment charges |
Protection | Isle of Man or Jersey deposit scheme, depending on booking |
The minimum opening deposit is £5,000 for GBP or 7,000 for each of EUR, USD and AUD.
There is no maintenance charge when the quarterly average remains at least that opening threshold, while falling below it costs £60, US$90, €90 or AU$90 quarterly.
For a GBP account, four below-threshold quarters would cost £240 before card, payment or exchange charges.
The optional Visa card costs £15, US$25, €20 or AU$25 annually, and cash withdrawals cost 1.75% subject to currency minimums.
This is a useful distinction when you need offshore standing orders or GBP direct debits, rather than a wallet that converts automatically between every balance.
Optimum sits outside CODI and the UK FSCS, with eligible deposits covered under the applicable Isle of Man or Jersey scheme up to £50,000.
Choose the funding and receiving route first
If your money starts in ZAR, Shyft or a linked local-bank account handles the currency purchase through a South African authorised dealer.
Funding an offshore account from rand can involve a local currency conversion followed by an international payment, with separate costs at each stage.
For any international receipt, give the sender the exact currency instructions and reference, because a mismatched wallet or account can cause rejection or conversion.
South African exchange-control requirements still apply when you buy foreign currency, with the payment purpose and allowance route recorded through the authorised dealer.
Our guide to large international transfers from South Africa explains the current allowance and tax-compliance process in more detail.
Compare account costs by the action you will take
A free account can still be expensive when its exchange spread, wire charge or card fallback applies to every payment.
Start with your normal action, such as receiving US$200 monthly, converting R10,000 for travel, or keeping GBP for a future bill.
Fixed wire fees consume more of a small receipt, while percentage charges grow with the amount and maintenance charges depend on the account’s balance rules.
For card spending, check whether the card selects the matching balance and what happens when that balance cannot cover the complete transaction.
Also separate an opening deposit from a fee, because the deposit remains your money while card and maintenance charges do not.
Local and offshore accounts use different protection
CODI covers qualifying foreign-currency deposits booked on a South African bank's balance sheet, subject to the scheme's product and depositor rules.
The R100,000 limit applies across qualifying deposits held by one depositor at one bank, and foreign-currency claims are reimbursed in rand.
That general protection should not be applied automatically to Shyft wallet balances, Wise electronic money or an account legally booked offshore.
Wise Payments Limited safeguards customer money as an FCA-authorised electronic money institution, but safeguarding is different from bank deposit insurance.
Optimum uses the applicable Isle of Man or Jersey deposit scheme, so confirm the booking entity when opening the account.
How to open and use a multi-currency account
Define the account job
Choose whether you need ZAR conversion, foreign receiving details, long-term holding, card spending or a bank account legally held offshore.
Check eligibility and entity
Confirm residence, existing-bank requirements, minimum funding and the legal entity that will hold or safeguard your money.
Match currencies to functions
Check which currencies can be held, received externally, converted and spent directly without an unexpected fallback to ZAR.
Price your normal action
Compare the exchange rate, wire charge, card fee, ATM cost, balance requirement and possible intermediary deductions for your expected use.
Confirm the first payment
Check the beneficiary details and full funding cost before your first payment, then confirm that it arrives in the intended currency.
Use the form below when a one-off international payment fits your need better than maintaining foreign-currency balances.
Compare international transfers from South Africa
Enter your destination and ZAR amount to compare the available rates for your international payment.Our methodology & why trust us
I compared ZAR funding, held currencies, foreign receiving, card access, account costs and the legal protection attached to each option.
We checked official account features and tariffs in September 2026, including eligibility, funding restrictions and the differences between local and offshore accounts.
We may earn commission from some companies, but commercial arrangements do not influence account positions or what I write.
Some services on the list are based on our research rather than internal testing.
You can read more about our process in our review methodology.
Sources
Cheapest ways to send money from South Africa
Use these ZAR2,000 examples to check the cost of smaller payments across eight common destinations.
Best money transfer services in South Africa
Choose the recipient method first, then decide whether you need a self-service payment or help with a more complex transaction.
Contributors
Please share your experience with …