We only list companies that are trustworthy and appropriately licensed. Our aim is to give you a comprehensive view of the regulated money transfer marketplace.
|Disclosure
MoneyTransfers aims to help users find the best money transfer provider for their needs. To support our free service, we may earn a commission from some of the providers listed in our search results. The commission may also impact the ordering of the providers shown. Our reviews are independent from this and are based on our editorial policy, research and testing of dozens of remittance providers on the market.
Table of Contents
For mobile money transfer abroad from Switzerland, you can pay in francs through a supporting service and deliver local currency into your recipient's registered wallet.
WesternUnion@SBB can take CHF cash at a ticket machine, while Swiss Bankers Send uses a Swiss Bankers card to fund supported wallet payments.
TWINT user payments serve a separate local-account task, so I suggest starting with whether you're repaying someone nearby or supporting a recipient abroad.
Search Now & Save On Your Transfer
Instantly view live exchange rates, fees & features.
At a glance
M-PESA in Kenya: local payments and agent cash withdrawals.
GCash in the Philippines: peso spending, with Swiss Bankers among the sending options.
bKash in Bangladesh: direct credit or a supported remittance claim.
MTN MoMo in Ghana: transfers into a personal mobile-money account.
eZ Cash in Sri Lanka: Swiss Bankers wallet delivery within the recipient's account allowance.
WesternUnion@SBB supports CHF cash funding as well as payment in its app.
What is a mobile wallet?
A mobile wallet keeps an electronic balance, although the account behind a phone payment can also be a bank account.
Knowing which account receives the money helps you choose the right transfer details and avoid an unnecessary second payment.
Mobile wallets
GCash and eZ Cash hold local currency for their account holders, who can use supported payment and withdrawal functions.
The recipient opens and verifies that account locally, while you can send from Switzerland through a service that supports it.
Mobile money
Mobile-money networks such as M-PESA connect a registered phone number to an account that supports local transfers and cash access.
An airtime top-up pays for mobile service, so choose wallet delivery when your recipient needs money they can spend or withdraw.
Money transfer apps
Money transfer apps arrange the international payment, taking your francs and supplying the quote, reference and available receiving methods.
The app you use to send and the wallet your recipient uses to receive do not have to be the same product.
Mobile banking apps
A banking app gives you access to a bank account, including domestic payments and any international transfers supported by that bank.
If you want to hold foreign currencies yourself, compare multi-currency accounts separately from paying into another person's overseas wallet.
Apple Pay and Google Pay
Apple Pay and Google Pay can pay a supporting transfer service through a linked card, without deciding the recipient's account type.
Your choice of bank deposit, wallet delivery or cash collection still determines where the international payment finishes.
Who handles the international transfer?
The sending service collects your payment in Switzerland and arranges conversion and delivery, while the overseas wallet controls access to the received balance.
For a delayed international payment, use the sending service's reference to contact support before asking the recipient to investigate their account.
WesternUnion@SBB lets you start the transfer in its app, then pay with CHF cash at a ticket machine or through an accepted app payment method.
Its Direct to Wallet option requires an active recipient wallet, with availability and maximum transfer amount depending on the destination.
I like having cash funding available, but I suggest comparing the converted recipient amount with a bank-funded service before booking.
Which recipient account fits your payment?
The right network depends on where the recipient holds money, rather than which sending app you prefer to use.
Mobile payments and cash access in Kenya
?
M-PESA
Fees
Exchange Rate Markup
Transfer Speed
Spending and bills in Philippine pesos
?
GCash
Fees
Exchange Rate Markup
Transfer Speed
Local payments and remittance cash withdrawals
?
bKash
Fees
Exchange Rate Markup
Transfer Speed
Personal mobile-money payments in Ghana
?
MTN MoMo
Fees
Exchange Rate Markup
Transfer Speed
Local rupee payments and cash withdrawal
?
eZ Cash
Fees
Exchange Rate Markup
Transfer Speed
M-PESA in Kenya
Send shillings to the account your recipient already uses
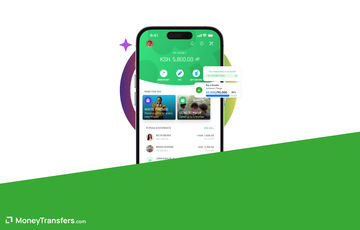
M-PESA connects a Kenyan mobile account with payments and agent withdrawals, so it can suit a recipient who uses the network for everyday expenses.
The account needs to be active and registered, with the recipient's name and mobile number matching the details you enter.
My suggestion is to keep the money in M-PESA when the recipient wants mobile payments, while comparing cash withdrawal costs when they need notes instead.
Sending to M-PESA from Switzerland
Wise, WorldRemit and Western Union support Kenyan M-PESA delivery, letting you arrange the overseas payment from Switzerland without opening a Kenyan account.
These CHF500 options help compare how many shillings reach the wallet when you send money from Switzerland to Kenya.
Last updated at 16.10.2026
CHF KES
Mid Market RateCHF 1 = KES 157.05
Transfer AmountCHF 500
1
Wise
2
Western Union
They get (after fees)
Transfer fees
FX Rate
Markup
Delivery time
KES 77'406.00
CHF 7.03
157.0190
0.02%
Within minutes
KES 76'151.00
CHF 0.00
152.3016
3.07%
Minutes - 2 days
How your recipient receives and uses the money
The shillings become available in M-PESA, where the recipient can make supported payments or arrange a withdrawal through an agent.
Wise caps M-PESA transfers at KSh250,000 each and KSh500,000 per day, with enough remaining recipient-account capacity also required.
A higher sender allowance does not remove those wallet-delivery limits, so use an eligible bank payment for an amount that will not fit.
GCash in the Philippines
GCash avoids another transfer before spending the pesos
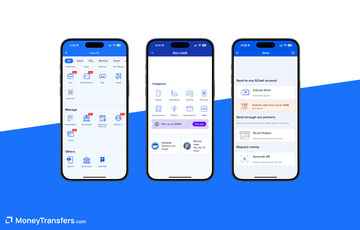
GCash is a Philippine wallet for spending, bills and supported local transfers, with overseas payments arriving through participating remittance services.
The recipient must have an active verified wallet, and moving the balance to a bank or withdrawing it may add a charge.
If they plan to pay bills through GCash, I suggest comparing direct wallet delivery before sending the money into a separate bank account.
Sending to GCash from Switzerland
Wise and WorldRemit support GCash delivery, while Swiss Bankers offers it through Send for people resident in Switzerland using a Swiss Bankers card.
Swiss Bankers charges CHF3 for a digital-wallet transfer, with currency conversion and any card-loading charge affecting the overall cost.
For CHF500, compare these alternatives when you send money from Switzerland to the Philippines into GCash rather than a bank.
Last updated at 16.10.2026
CHF PHP
Mid Market RateCHF 1 = ₱ 76.2592
Transfer AmountCHF 500
1
Wise
They get (after fees)
Transfer fees
FX Rate
Markup
Delivery time
₱ 37'868.91
CHF 3.38
76.2533
0.01%
Within minutes
How your recipient receives and uses the money
The recipient receives pesos inside GCash and can use available payment functions, or pay any applicable charge to move or withdraw the balance.
Wise and WorldRemit limit each wallet transfer to ₱50,000, even if the recipient's GCash account has a higher overall allowance.
Swiss Bankers wallet delivery takes up to two hours after successful processing, with loading your sending card forming a separate step.
bKash in Bangladesh
Agree whether the recipient expects credit or a remittance claim
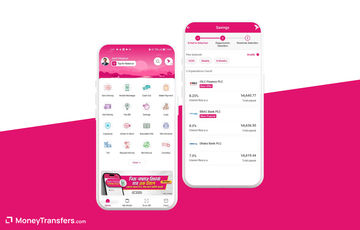
bKash gives your recipient a taka balance for local payments and withdrawals, with international remittances handled through supporting companies.
Some payments go directly into the wallet, while a Western Union remittance can require the recipient to claim it through bKash.
That difference is worth settling before paying, especially if the recipient is waiting for the money to appear automatically.
Sending to bKash from Switzerland
Wise and WorldRemit support bKash delivery, with Western Union also offering the network through its remittance service.
For a Western Union claim through bKash, the recipient needs an active account registered using their National ID and the transfer details.
Compare CHF500 payments for sending money from Switzerland to Bangladesh, then select the bKash receiving method offered by your chosen company.
Last updated at 16.10.2026
CHF BDT
Mid Market RateCHF 1 = ৳ 148.7658
Transfer AmountCHF 500
1
Wise
2
Western Union
They get (after fees)
Transfer fees
FX Rate
Markup
Delivery time
৳ 73'499.36
CHF 5.88
148.7480
0.01%
Next day
৳ 72'741.00
CHF 0.00
145.4814
2.23%
Minutes - 2 days
How your recipient receives and uses the money
Once credited or claimed, the taka can fund supported local payments or be withdrawn through bKash's available cash-out channels.
Wise's bKash limits are Tk250,000 per day and Tk450,000 per month, so check the recipient's remaining allowance before sending another payment.
For remittance withdrawals at participating ATMs, taking out Tk5,000 costs Tk35, which should be included if the recipient needs cash.
MTN MoMo in Ghana
Use personal-wallet delivery for family support
MTN MoMo holds a Ghanaian mobile-money balance that your recipient can use through supported local payments and cash-out services.
Choose the MTN network and confirm the registered number, because another Ghanaian phone number can belong to a different wallet operator.
In my opinion, this suits a recipient's own expenses when they already use MoMo, with a separate option for paying a business account.
Sending to MTN MoMo from Switzerland
WorldRemit and Western Union support sending to MTN Mobile Money, with the chosen delivery method controlling where the cedis arrive.
These CHF500 options compare personal mobile-money receipt when you send money from Switzerland to Ghana, rather than cash collection.
Last updated at 16.10.2026
CHF GHS
Mid Market RateCHF 1 = GH₵ 14.0751
Transfer AmountCHF 500
1
Western Union
They get (after fees)
Transfer fees
FX Rate
Markup
Delivery time
GH₵ 6'883.46
CHF 0.00
13.7669
2.21%
Minutes - 2 days
How your recipient receives and uses the money
The recipient can access the cedis in their MoMo account, then spend through supported payments or withdraw through a cash-out channel.
WorldRemit has a GH₵15,000 transfer cap and accepts personal MTN wallets for international delivery, rather than MTN business wallets.
Check the recipient's account allowance as well, because their tier and earlier payments can reduce how much they can accept.
eZ Cash in Sri Lanka
eZ Cash needs a smaller payment that fits the account tier
Dialog's eZ Cash holds Sri Lankan rupees for local payments and withdrawals, with incoming remittances available to participating Dialog and Hutch accounts.
The recipient must be an adult resident of Sri Lanka and the registered owner of the mobile number attached to the account.
I suggest starting with the wallet's inward-remittance allowance here, because converting several hundred francs can exceed what the recipient is able to receive.
Sending to eZ Cash from Switzerland
Swiss Bankers Send supports eZ Cash delivery, funded using a Swiss Bankers card by someone resident in Switzerland.
The digital-wallet sending charge is CHF3, so check the converted rupees and any card-loading cost alongside that fee.
When you send money from Switzerland to Sri Lanka, a bank deposit is another choice if the eZ Cash receiving allowance is too small.
How your recipient receives and uses the money
Incoming eZ Cash remittances arrive in rupees, with an SMS notifying the recipient before they use local payment or withdrawal functions.
The inward-remittance daily limit is Rs50,000 for a Classic account and up to Rs150,000 for a Power account.
Cash withdrawal uses the applicable eZ Cash tariff, so the received balance and the amount collected as notes can differ.
Sending money locally with TWINT
TWINT lets you send to another TWINT user through a contact or mobile number, making it suitable for repayments and splitting a bill.
Its bank apps can link to your bank account, while the prepaid version works with a loaded balance.
A TWINT user payment and an international transfer into eZ Cash or M-PESA follow different account systems, even though both use mobile numbers.
For a local payment, my suggestion is to use the account you already have rather than add an international remittance service to the process.
What fees should you compare?
Compare the francs you pay with the recipient's usable local currency, including the sending fee, conversion and any funding or withdrawal charge.
WesternUnion@SBB Direct to Wallet starts at CHF5, with Western Union also earning from currency exchange, so the fee alone does not show total cost.
Swiss Bankers' CHF3 digital-wallet fee similarly excludes any separate card-loading charge, which can affect whether it suits a smaller payment.
If the recipient will pay directly from the wallet, compare that use with cash collection rather than automatically adding a withdrawal to every payment.
When can the recipient use the money?
For fast transfers abroad from Switzerland, the sending service must receive your payment before overseas delivery, so include funding in your arrival estimate.
With a loaded Swiss Bankers card, you avoid waiting to load it for that payment, although the transfer still has its processing time.
If you use a WesternUnion@SBB ticket machine, its payment QR code is valid for one hour, so complete the funding step within that window.
Wallet credit and cash withdrawal are separate stages, with the recipient's chosen outlet determining when they can collect notes.
Which limits apply to the transfer?
Check the company's converted-amount cap and the recipient's remaining receiving allowance, together with how much their wallet can hold.
For eZ Cash, the account tier changes the inward-remittance limit, while GCash payments through Wise have their own per-transfer cap.
Do not split a payment before checking the daily and monthly allowance, because several smaller transfers can still exceed it.
How to make a mobile money transfer from Switzerland
Identify the exact wallet
Confirm the recipient's country, account operator, registered name and number, then check that they can access and use the account.
Set the amount in francs
Ask the recipient to check their remaining receiving allowance and compare it with the local-currency amount in your intended transfer.
Choose how to fund the payment
Compare a bank or card payment with an available cash-funded transfer, including any extra charge and the time needed to pay.
Book the correct receiving method
Select the named wallet and check whether delivery credits it automatically or requires the recipient to claim a remittance.
Keep the reference and confirm receipt
Save the transfer reference after paying, then confirm the recipient has received the balance before making another payment.
What if a wallet transfer has not arrived?
Start with the company that accepted your payment, giving it the reference, amount and recipient details so support can trace the transfer.
For a claim-based remittance, confirm that the recipient has the required reference and has completed the claim inside the correct wallet.
If a phone number is wrong, contact the sending service immediately because recovering a completed payment can be difficult.
The wallet should handle access problems after receipt, including a blocked account, lost SIM or failed recipient verification.
Is mobile money transfer safe?
Check the company taking your payment and its regulatory status, including the relevant Swiss authorisation or recognised self-regulatory organisation where applicable.
FINMA-recognised SRO supervision covers anti-money-laundering obligations, so do not treat SRO membership as the same protection as a Swiss bank deposit.
The overseas mobile account also has its own protection and access rules, which remain relevant after the remittance reaches the recipient.
Call the recipient if their payment details change unexpectedly, and keep wallet PINs and banking authentication codes out of messages.
Compare the francs you pay for an overseas transfer, then confirm that the selected service supports your recipient’s mobile wallet.
Compare transfers from Switzerland
Enter your CHF amount and destination to compare available transfer rates, then check wallet delivery with your selected service.
Our methodology & why trust us
We checked Swiss funding options and named-wallet delivery, then compared recipient functions, account allowances and the charges attached to using the balance.
MoneyTransfers data supplies international-company comparisons, with native wallet costs and Swiss Bankers fees assessed from their product information.
My selections focus on where your recipient can use the money, while our review methodology explains the wider assessment process.







Please share your experience with …