
The Best Multi-Currency Accounts in Colombia in 2026
Table of Contents

Author: Artiom Pucinskij
Table of Contents
Wise is my pick for receiving supported foreign income and keeping several currencies, provided you can use bank payments rather than a locally issued card.
Paysera offers another currency-holding payment account, while Dukascopy provides a Swiss bank account with a wider set of held balances.
Bancolombia Panamá is a different option for keeping dollars within a banking relationship, because its personal account holds USD rather than multiple currencies.
The shortlist is shorter than in some markets, and Colombian residence eligibility does not automatically include local peso funding or a spending card.
Search Now & Save On Your Transfer
Instantly view live exchange rates, fees & features.
At a glance
Wise: supported foreign receipts and several held currencies
Paysera: currency holding and bank payments
Dukascopy: multiple balances within a Swiss bank
Bancolombia Panamá: USD-only personal bank alternative
Accounts for keeping foreign currencies
These options cover different receiving and payment arrangements, with the dollar-only bank account labelled separately from accounts holding several currencies.

"Over 15 million customers use Wise, mostly for their excellent mobile app, transparent fee structure & use of mid-market rates. Now increasingly used for larger transfers."
Wise
My pick for keeping foreign income in its original currency
Wise lets Colombian residents receive supported foreign-currency payments and retain the balance, which can avoid converting each receipt into pesos immediately.
You can later exchange the money or make a supported bank payment when you need it.
Feature | Details |
|---|---|
Held currencies | 40+ currencies, including USD, EUR and GBP, no COP balance |
Receiving | Currency-specific account details, including local USD, EUR and GBP receipts |
Card | Not issued to residents of Colombia |
Main cost | No account subscription, conversion fee and charges for some incoming payment methods |
Protection | Safeguarded electronic money, rather than insured bank deposits |
Eligibility | Colombian residents can hold balances, subject to identity checks |
I like Wise for foreign income you expect to spend through bank payments or convert later.
Its local receiving instructions can reduce payment friction when an employer or client can use the supported domestic transfer system.
Receiving a domestic dollar payment differs from receiving a dollar wire, which carries a US$6.11 Wise charge.
Euro and sterling SWIFT receipts also have fixed charges, so share the instructions for the payment method you intend to receive.
Converting a balance uses the mid-market rate plus a separate fee, while keeping the same currency avoids that conversion step.
The main limitation for a Colombian resident is the absence of a Wise card, so this account will not replace a travel debit card.
COP is not a supported currency for adding money, even though Colombian residents can hold foreign balances.
Check the available deposit currency before moving money from a Colombian bank, since foreign bank-transfer costs can change the total.
Wise is a regulated electronic-money service, and its safeguarding arrangement differs from the deposit insurance attached to a bank savings account.
Paysera
Good for holding currencies alongside euro bank payments
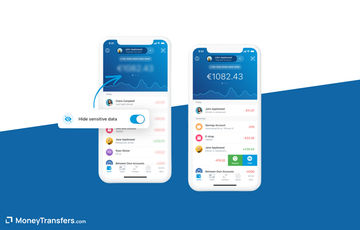
Paysera combines multiple currency balances with euro bank-payment access, which can suit someone receiving or making payments connected to Europe.
Colombian applicants can open personal accounts, although enhanced identity checks and ongoing monitoring apply.
Feature | Details |
|---|---|
Held currencies | Multiple balances, exchange available in 30+ currencies |
Receiving | EUR IBAN and supported currency-specific bank instructions |
Card | Colombian residence does not qualify for its EEA-issued Visa card |
Main cost | Free digital opening and active account administration, exchange and payment charges vary |
Protection | Safeguarded electronic money under Lithuanian regulation |
Eligibility | Colombian personal applicants, subject to enhanced checks and approval |
I'd say consider Paysera for recurring euro bank payments if you want to keep other supported currencies in the same account.
The euro IBAN can help with receiving euros and making supported European transfers, but it does not give every balance its own domestic receiving route.
For other currencies, follow the account’s bank instructions before asking a payer to send money.
Paysera’s exchange quote and payment fees need checking together, because free account administration does not make every international transaction free.
An unused account can attract inactivity charges, so this is better suited to an account you continue to access.
Prepare identification and any requested source-of-funds information before relying on it for a time-sensitive payment.
The Visa card requires EEA residence, including its digital version, so Colombian account access does not provide a card for travel spending.
Funding from Colombia can also require a bank transfer with charges from the sending bank or intermediaries.
Paysera LT is a licensed Lithuanian electronic-money institution, and safeguarding protects customer funds differently from a bank deposit-insurance scheme.
Dukascopy Bank
Best here for a Swiss bank account with several currency balances
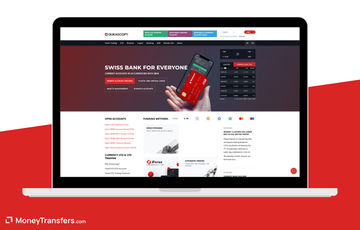
Dukascopy offers Colombian residents a Swiss bank account that can hold 24 currencies, including dollars, euros and Swiss francs.
It can receive and send international bank payments, giving it a broader holding role than a dollar-only savings account.
Feature | Details |
|---|---|
Held currencies | 24, including USD, EUR, GBP and CHF, no COP |
Receiving | Swiss bank details and supported international payment routes |
Card | Separate prepaid products with their own eligibility, currencies and fees |
Main cost | €1 monthly unless waiver conditions apply, conversion and bank-payment charges |
Protection | Eligible Swiss bank deposits protected up to CHF100,000 per client |
Eligibility | Colombian residents can apply, adult functions require verification and approval |
I think Dukascopy is worth considering when holding several currencies in a bank account is more important to you than low-cost everyday card spending.
Opening requires identity checks and video verification, and a requested €40 initial deposit becomes money in the account rather than an opening fee.
The monthly maintenance charge can be waived under the bank’s loyalty conditions, so check those conditions before assuming the account is free.
Currency exchange incorporates a 0.5% spread plus a volume-based commission, with a 1% commission in the first US$10,000 monthly tier.
That combined charge can make frequent small conversions more expensive than the headline interbank-rate wording suggests.
Outgoing dollar bank payments cost US$19 with shared charges or US$35 with the sender-paid charge option, before possible external charges.
Frequent third-party receipts or large, complex payments can incur additional charges and require supporting documents.
Before using it for repeated income payments, I'd say confirm those receiving costs and keep card costs separate from the bank-account comparison.
Bancolombia Panamá
A dollar-only alternative for Colombian nationals
Bancolombia Panamá provides a personal US-dollar account that Colombian nationals resident in Colombia can open through the group’s digital channels.
It lets you retain dollars and make or receive bank transfers, although it does not hold a range of foreign currencies.
Feature | Details |
|---|---|
Held currencies | USD only |
Receiving | International bank transfers using the account’s payment instructions |
Access | Mi Bancolombia and supported investment banking channels |
Main cost | US$0 opening minimum, maintenance conditions depend on the chosen account |
Regulation | Bancolombia Panamá S.A., supervised by Panama’s banking regulator |
Eligibility | Colombian nationality and cédula, Colombian resident, with income documents and approval |
I'd say consider this account when your foreign income or savings are mainly in dollars and you want a bank account within the Bancolombia group.
You can apply online, so opening does not require a trip to Panama or a US$5,000 deposit.
The bank asks for income documents, such as an employment letter or the relevant documents for a pensioner or self-employed applicant.
Its requirements also exclude applicants with Panamanian residence, tax residence or economic activity, which narrows who can use this product.
Free access to the digital channels does not establish that every international transfer or account plan has no charge.
Check the chosen plan’s maintenance conditions and payment tariff before deciding how much money to keep there.
The US$5,000 figure attached to its interest information is an interest-earning balance threshold, rather than the opening minimum.
Your account belongs to the Panamanian subsidiary, so Colombian Fogafín protection for domestic deposits should not be assumed to cover it.
Use the bank’s incoming-transfer instructions when arranging a dollar payment, and check whether the sending bank will deduct intermediary charges.
Choose the currency around your future expenses
For European tuition paid in euros, I suggest comparing a direct peso-to-euro conversion before using dollars as an intermediate savings currency.
Buying dollars first and converting them into euros later can create another conversion charge without matching the currency of the bill.
Holding euros avoids that extra conversion when the tuition payment becomes due, but the peso value can still change while you hold them.
For Colombian bills, keep enough accessible pesos rather than relying on converting a foreign balance during an urgent payment.
The same principle applies to foreign income, where keeping some dollars can make sense if future expenses are also in dollars.
Receiving foreign income needs the right account details
A held dollar balance does not prove that an employer can pay it through a domestic US bank transfer.
Check whether the account provides local receiving details or requires a SWIFT wire, including charges for that specific incoming method.
Confirm that the payer and account names fit the service's rules, especially when a payment comes from a company or investment platform.
Before directing your salary into a new account, my suggestion is to check how you will withdraw pesos and the full cost of that conversion.
A low incoming fee can be outweighed by later conversion or withdrawal charges, so assess the complete route into your Colombian account.
Holding, card spending and protection are separate features
An account can let you hold euros without giving Colombian residents a card, which leaves bank payments as the way to use the balance.
A card can also spend through a local-currency account rather than directly using the foreign money shown elsewhere in the app.
Check the selected balance and conversion steps before assuming that a foreign purchase avoids exchanging the money again.
For protection, identify the legal entity holding each balance rather than assume a Colombian licence covers every foreign service under the same brand.
I suggest checking the product's deposit or safeguarding arrangements before keeping a substantial balance, especially where the foreign account is operated abroad.
For a one-off payment rather than ongoing holding, international money transfer services from Colombia covers the available bank and cash-delivery choices.
How to check a multi-currency account
Match the currencies to your expenses
List the currencies you receive and will spend, checking whether a direct conversion avoids moving through another foreign currency first.
Confirm Colombian residence eligibility
Check that the personal product accepts your residence, and separate holding eligibility from the availability of a card or local peso funding.
Check the receiving instructions
Ask whether your payer should use a domestic payment or foreign wire, including the relevant account name and charges for that method.
Follow the money into pesos or spending
Check the conversion and withdrawal steps, including whether a card uses the foreign balance directly or spends through a different currency account.
Verify the legal entity and costs
Identify the company holding the foreign balance, then add account charges and conversion costs before deciding how much money to keep there.
Check the cost of converting and sending pesos
Compare the cost of converting and sending money before moving a balance between currencies or paying another account abroad.
Find the best rate for transfers from Colombia
Enter your destination and amount to compare current COP transfer costs.Our methodology & why trust us
These selections assess personal foreign-currency holding options for Colombian residents, with local funding, incoming payments and spending checked as separate features.
Official eligibility, account terms and fee schedules establish the product details, while our current Colombian-origin live results support conversion components where eligible data is available.
Conversion and transfer quotes do not establish account protection or incoming payment fees, so those checks remain part of each account's assessment.
Read about how we review accounts and companies for the evidence used in our comparisons.
Sources
Best money transfer companies
These services accept outbound payments, with bank delivery and cash access kept separate so you can choose around the recipient's needs.
Best money transfer apps
Global66 suits a separate transfer account, while the bank apps make more sense when their account and payment options already fit you.
Contributors

Please share your experience with …