
The Best International Money Transfer Services In Kenya in 2026
Table of Contents
Author: Artiom Pucinskij
Table of Contents
M-PESA Global is my first choice when you already use M-PESA and want to send directly to a supported overseas wallet.
For a payment needing branch assistance, I would choose Co-opRemit, while KCB or Absa can suit transfers from an existing bank account.
Western Union through Equity is the better fit when your recipient needs cash collection or another delivery method beyond a standard bank deposit.
Search Now & Save On Your Transfer
Instantly view live exchange rates, fees & features.
At a glance
These are the best money transfer services for international transfers in Kenya right now:
Wallets, bank accounts and partner cash pickup: M-PESA Global
Branch-assisted bank or mobile-wallet payments: Co-opRemit
Cash pickup from an online bank transfer: Western Union through Equity
Transfers to regional Equity accounts: Equity Bank
Direct transfer from a KCB bank account: KCB
Choosing who pays bank charges: Absa Kenya
Best services for sending money abroad from Kenya
Choose the route around the recipient method first, because a strong wallet service can still be useless for a university or overseas bank account.
M-PESA Global
M-PESA Global can send to supported wallets, banks and cash partners from your phone.
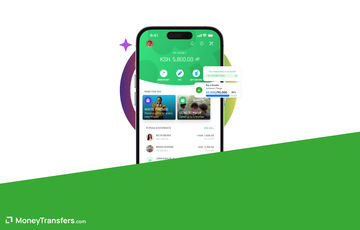
Active registered M-PESA users can opt into the service through the app or *334#, which keeps the transfer within an established local account.
Direct mobile-number destinations include Uganda, Tanzania, Rwanda, Botswana, Burundi, Zambia and Malawi, alongside Bangladesh and Pakistan.
Western Union adds bank deposits and cash collection, while TerraPay supports Bangladesh and Pakistan bank or mobile payments through the same M-PESA account.
Eligible individual customers can also send to an Alipay beneficiary in China, giving the service a useful route beyond family remittances.
Safaricom Money Transfer Services Limited operates the service with international transfer partners, so destination-specific partner restrictions and beneficiary charges can apply.
Prices and delivery estimates vary by partner route, so use the app's Global cost estimator for the selected country and transaction.
I would choose it over a bank for an eligible wallet recipient, especially when cash collection and SWIFT details would only add unnecessary steps.
For a tuition or medical payment needing document assistance, I would choose Co-opRemit or your bank rather than handling everything through a wallet.
Co-opRemit
Co-opRemit offers branch help for bank and mobile-wallet payments, including tuition and medical transfers.
Co-operative Bank customers start the transfer at a branch with identification and the beneficiary details required for the selected destination.
The recipient can receive a foreign bank deposit or supported mobile-wallet payment, which covers more formal use cases than a regional wallet-only route.
The service has a KES 1,000,000 daily maximum and a USD 2.50 to USD 12.50 fee range, with exceptions for Tanzania and Zambia.
That fee still does not show the whole cost, because the live exchange rate and any receiving-bank deductions affect what arrives.
Branch initiation is less convenient than M-PESA Global, but it can help with tuition or medical payments requiring beneficiary and purpose documents.
I would choose Co-opRemit when the recipient needs a bank account and the amount fits its daily limit, then compare the delivered value with my bank.
Ask the branch for the recipient amount and delivery estimate in writing, especially when an institution requires an exact foreign-currency payment.
Western Union through Equity
Western Union through Equity lets you arrange cash-collection transfers online.
Equity customers can start an international transfer through Equity Mobile or Equity Online, avoiding a branch visit for an eligible payment.
M-PESA Global also connects to Western Union, while this Equity route funds the transfer from an eligible bank account through Equity's digital channels.
Delivery choices include a foreign bank account, an Equity account in a supported regional market and cash pickup through Western Union agents.
That flexibility helps when the recipient has no suitable bank or wallet, although the available choice still depends on the destination.
Cash pickup requires the correct transfer reference and matching identification, so send the recipient details through a secure channel.
The final fee, exchange rate and timing depend on the configured route, which makes a cash quote unsuitable for judging bank-deposit value.
I would compare it with M-PESA Global for a regional wallet recipient and with Co-opRemit for a normal overseas bank payment.
Equity Bank
Equity Bank works well when the recipient already has an Equity account in the region.
Borderless Banking sends to Equity accounts in Uganda, Tanzania, Rwanda and South Sudan through branch, mobile or online channels.
This intra-group route can be simpler than collecting full correspondent-bank instructions when the recipient already uses Equity in one of those markets.
This route is distinct from Western Union through Equity, which adds cash pickup and other destination-dependent delivery methods.
I would choose Borderless Banking for a matching regional Equity recipient, then use KCB or Absa for a formal global bank payment.
Before sending, confirm the eligible destination, recipient account, transfer currency, fee and any conversion applied between the two Equity markets.
KCB
Existing KCB customers can transfer directly from KES or foreign-currency accounts.
Its international transfer route can be accessed through KCB Internet Banking, which suits an overseas beneficiary needing a standard bank deposit.
Sending from a foreign-currency account can avoid converting KES at the moment of transfer, provided you already hold the required currency.
If you fund from KES, the exchange rate and bank charges need comparing with Co-opRemit and Equity for the same recipient amount.
The beneficiary bank may also deduct correspondent charges, so a low sending fee does not guarantee that the full invoice arrives.
KCB separately offers partner networks for cash, wallet and card delivery, but those options need their own destination-specific quotes.
I would use KCB’s direct bank route for an overseas invoice and its remittance partners when the recipient needs cash or another payout method.
Absa Kenya
Absa Kenya lets you choose who pays the international bank charges.
Its Internet Banking transfer flow asks for the payment reason and lets the sender choose sender-paid, beneficiary-paid or shared charges.
That choice is useful for tuition and medical bills where an unexplained deduction can leave the payment short.
Sender-paid charges can improve the chance of a full-value arrival, although correspondent banks may still apply costs outside Absa's control.
Beneficiary-paid or shared charges may reduce your initial KES payment, but they shift uncertainty to the person or institution receiving it.
I would choose Absa for an existing account and an exact-value bank payment, after confirming how the selected charge option works on that route.
The transfer screen should show the applicable exchange rate, bank fee and required beneficiary information before you approve the instruction.
How to choose a Kenya international transfer service
Start with the recipient method
A regional mobile wallet, cash pickup and overseas bank account require different networks, even when the same bank presents them together.
Use M-PESA Global for a listed wallet destination, Western Union through Equity for cash, and a bank route for a formal account payment.
Our guide to money transfer apps in Kenya covers mobile setup and app experience separately from this wider service comparison.
Check the regulated Kenyan route
Banks should appear in the Central Bank of Kenya's licensed-bank directory, while non-bank remittance companies need the appropriate local authorisation.
M-PESA Global operates through Safaricom Money Transfer Services Limited and international partners, which is different from an unrelated service merely accepting M-PESA funding.
The Central Bank warns against unlicensed money or value transfer services, including informal operators that cannot show an authorised legal entity.
Compare the amount that arrives
Check the sender fee, exchange rate and recipient amount together, then ask whether an overseas or correspondent bank may deduct more.
Kenyan transfer charges can also include tax applied to the service fee, so compare the final KES debit rather than the headline fee alone.
Our guide to the cheapest ways to send money abroad from Kenya explains the cost calculation in more detail.
Prepare the beneficiary details first
Wallet routes usually need a supported mobile number, while cash collection needs the recipient's legal name and accepted identification.
Bank transfers can require an account number, bank address, SWIFT code and payment reference, with extra evidence for tuition or medical bills.
Cheapest international money transfer services in Kenya
Co-opRemit is worth considering for a bank payment, but its transfer fee alone cannot establish whether it offers the best value.
Service | Cost information available before sending | Cost detail to compare |
|---|---|---|
M-PESA Global | Quote in the app or USSD flow | Fee, exchange rate and possible beneficiary charge |
Co-opRemit | USD 2.50 to USD 12.50 fee range, with country exceptions | Live rate and possible receiving-bank deduction |
Western Union through Equity | Route-specific quote | Cash versus bank pricing and recipient method |
Equity Borderless Banking | Bank quote | Transfer currency, fee and any conversion |
KCB international transfer | Bank quote | KES conversion and overseas-bank deductions |
Absa international transfer | Internet Banking quote | Sender-paid, beneficiary-paid or shared charges |
For a bank payment, give each service the same KES budget and compare the foreign currency arriving after every disclosed charge.
For cash or wallet delivery, compare only like-for-like recipient methods because their pricing and collection costs can differ substantially.
Fastest international money transfer services in Kenya
For an urgent wallet payment, I would choose M-PESA Global if its delivery estimate meets the deadline, then confirm the recipient can access the money.
Transfer route | When it can be the quickest fit | What can delay it |
|---|---|---|
M-PESA Global | Direct transfer to a listed mobile wallet | Partner review, destination limits and recipient-wallet checks |
Western Union through Equity | Cash collection on an eligible route | Identity review, agent hours and cash availability |
Equity Borderless Banking | Recipient holds an eligible regional Equity account | Account checks and regional processing |
Co-opRemit | Branch documents are complete before submission | Branch cut-off, beneficiary review and receiving institution |
Bank transfer through KCB or Absa | Formal overseas bank payment | Cut-off times, correspondent banks and compliance review |
Domestic M-PESA speed does not guarantee the international leg, so use the delivery estimate for the exact destination and recipient method.
Our guide to the fastest ways to send money abroad from Kenya covers urgent routes and timing checks in more detail.
Easiest services for sending money abroad from Kenya
The easiest route is the one matching your existing account and recipient details, because opening another service can add identity checks.
Your situation | My pick | Why it can be easier |
|---|---|---|
Sending to a listed regional wallet | M-PESA Global | Uses an active M-PESA account and mobile number |
Paying a foreign bank account with branch help | Co-opRemit | Staff can review beneficiary and purpose details |
Recipient needs cash pickup | Western Union through Equity | Online initiation with a broad agent network |
Recipient has a regional Equity account | Equity Borderless Banking | Avoids a standard global SWIFT instruction |
Existing KCB customer | KCB international transfer | Uses the customer's current bank account |
Exact-value payment with charge control | Absa | Lets the sender allocate international bank charges |
Best services for large transfers from Kenya
I would use a bank for a large personal transfer, because source-of-funds checks and beneficiary documents need handling before the money moves.
Co-opRemit's KES 1,000,000 daily limit gives you a clear boundary, while Equity, KCB and Absa require a route-specific limit check.
Large-transfer situation | Route I would check | Main reason |
|---|---|---|
Amount within KES 1,000,000 daily limit | Co-opRemit | Public cap with bank or wallet payout |
Regional recipient has an Equity account | Equity Borderless Banking | Direct intra-group account route |
Global bank beneficiary | KCB or Absa international transfer | Bank handling for documents and source of funds |
Institution must receive a fixed amount | Absa or another bank SWIFT route | Charge-allocation choice and formal payment reference |
Ask the bank to review your source-of-funds evidence and beneficiary instructions before converting KES or committing to a deadline.
For a university or medical provider, include the student or patient reference exactly and confirm the amount the institution expects to receive.
How to send money abroad from Kenya
Choose the recipient method
Confirm whether the recipient needs a mobile-wallet deposit, cash collection, regional bank transfer or global SWIFT payment.
Check the service and destination
Use the official app, website or bank channel to confirm Kenya-origin eligibility, KES funding and the exact destination.
Prepare the details
Gather your identification, source-of-funds evidence and the beneficiary information required for the selected payment method.
Compare the complete quote
Check the total KES debit, exchange rate, sender fee, recipient amount, possible deductions and delivery estimate together.
Pay and keep the reference
Follow the named funding instructions, then save the receipt and tracking details until the recipient confirms the full amount.
Choose the route that fits your recipient, then compare its full KES cost with another regulated service offering the same delivery method.
Compare money transfers from Kenya
Enter your destination and amount to compare the available rates for your KES transfer.Our methodology & why trust us
I selected these services around distinct Kenya-origin tasks, including regional wallets, cash collection, branch help and direct international bank payments.
Our research checked the regulated Kenyan entity, KES funding route, recipient methods, public limits and official customer process for each option.
Terms and transfer times can change with the destination, amount, delivery method, banking hours and required compliance checks.
We may earn commission from some companies, but commercial agreements do not influence their position or what I write about them.
Some services on the list are based on our research rather than internal testing.
You can read more about our process in our review methodology.
Sources
Cheapest ways to send money abroad from Kenya
The cheapest route delivers the most after matching the KES amount, destination, funding method and recipient outcome.
Best multi-currency bank accounts in Kenya
Most Kenyan options are separate foreign-currency accounts rather than one wallet pooling every currency behind a single card.
Contributors
Please share your experience with …